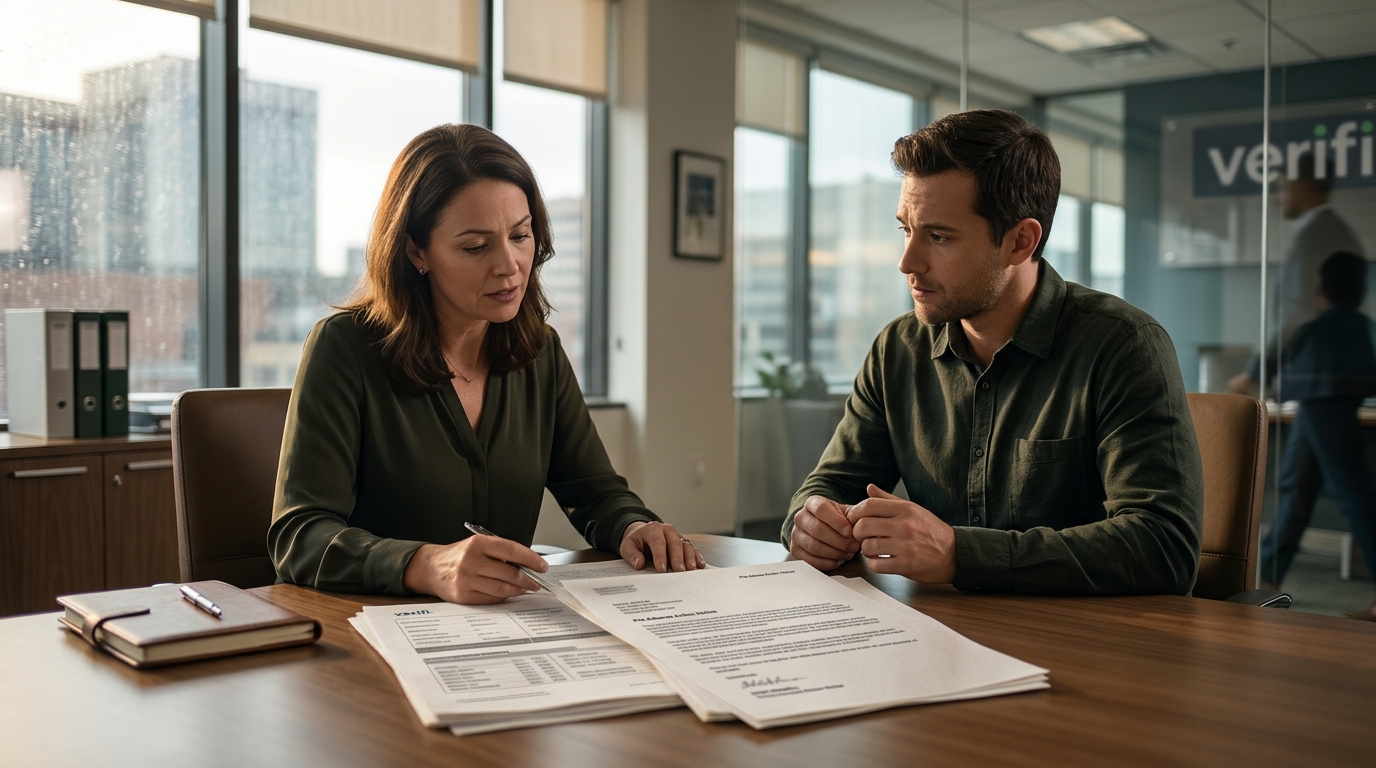
When a background check reveals disqualifying information, organizations must follow strict legal protocols before rejecting a candidate. The Fair Credit Reporting Act (FCRA) mandates a two-step process: providing a pre-adverse action notice and allowing the candidate time to respond. Skipping these steps exposes employers to significant legal liability and financial penalties.
Understanding Adverse Action
Adverse action is a formal decision to deny employment, promotion, or housing based on information in a consumer report. This term is legally defined under the FCRA as any action taken against a consumer based on information in a consumer report. Organizations must treat every negative result as a potential adverse action event. This classification triggers specific notification duties that protect consumer rights.
The legal framework exists to ensure fairness and accuracy. It gives individuals the chance to correct errors or provide context. For example, a criminal record might be expunged or sealed, rendering it legally irrelevant. Ignoring these nuances can lead to wrongful denials. Compliance is not optional; it is a mandatory legal standard for all entities using consumer reports.
The Pre-Adverse Action Notice
Reasonable time is typically interpreted as five business days, though some states require longer. During this window, the candidate can contact the screening agency to dispute data. They can also provide additional context to the employer. For instance, a gap in employment might be explained by a medical leave. This step ensures the decision is based on accurate and complete information.
Final Adverse Action Requirements
Common Compliance Mistakes
Many organizations fail due to procedural errors. One common mistake is skipping the pre-adverse action step. Employers often rush to deny candidates immediately after receiving a report. This violates the FCRA and exposes the company to lawsuits. Another error is failing to provide the consumer report copy. The candidate must see the exact data used to make the decision.
Timing is another frequent issue. Sending the final notice before the dispute window closes is a violation. Organizations must wait for the response period to expire. Additionally, using non-compliant language in notices can create ambiguity. Clear, plain language is essential. These mistakes are preventable with proper training and standardized workflows.
Key Takeaways
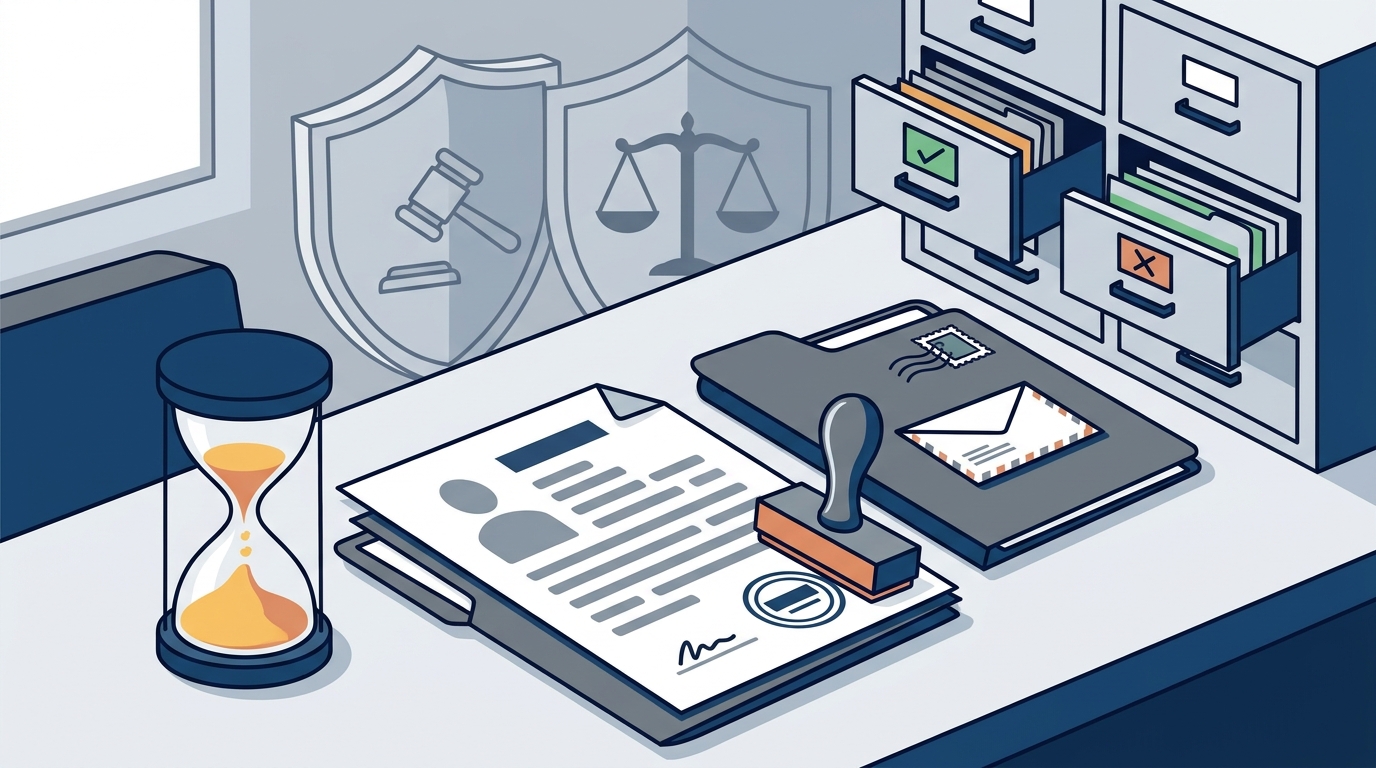
- Adverse action is a legal process triggered by negative consumer report findings.
- A pre-adverse action notice must be sent before any final decision is made.
- Candidates must receive a copy of the report and a summary of rights.
- A reasonable waiting period, typically five business days, is required for disputes.
- Statutory damages can result from failure to follow FCRA procedures.
- Standardized templates and training reduce the risk of compliance errors.
Frequently Asked Questions
What is among the difference between pre-adverse and final adverse action?
Pre-adverse action is a preliminary notice allowing the candidate to dispute the report. Final adverse action is the formal denial of employment or housing. The pre-adverse step is a mandatory waiting period before the final decision can be issued.
How long must I wait before issuing a final adverse action notice?
There is no fixed federal number of days, but five business days is among the standard reasonable period. Some states may require longer. The organization must wait for this period to expire before sending the final notice.
Do I need to send the consumer report with the pre-adverse notice?
Yes, the FCRA requires that a copy of the consumer report be provided with the pre-adverse action notice. This allows the candidate to review the specific data that triggered the adverse action.
What happens if the candidate disputes the report?
The consumer reporting agency must reinvestigate the disputed information. The organization should pause the hiring process until the reinvestigation is complete. If the information is corrected, the adverse action may be withdrawn.
Can I deny a candidate without following adverse action procedures?
No, if the decision is based on a consumer report, you must follow FCRA adverse action procedures. Failure to do so can result in legal liability and statutory damages.
Does the FCRA apply to all types of background checks?
The FCRA applies to consumer reports used for employment, housing, or insurance purposes. It does not apply to non-consumer reports, such as those used for business-to-business transactions.
Conclusion
Navigating adverse action procedures requires precision and legal awareness. Organizations must prioritize compliance to protect both their business and their candidates. By following the FCRA guidelines, you ensure fairness and reduce legal risk. For reliable background screening and compliance support, visit 2verifi to learn more about our services. Learn more: 2verifi com.